
Central Coast Multifamily: Q1 2026 Market Report
Q1 2026 Central Coast multifamily: 18 sales of 5+ unit buildings for $307 million, plus 17 South Santa Barbara County 2–4 unit sales.
From the multifamily sections (5+ units and 2–4 units) of the Radius Commercial Real Estate Q1 2026 Quarterly CRE Market Report, as published on radiusgroup.com. Passages have been removed where marked […].
Multifamily Investments: 5+ Units
Contribution by Jack Gilbert
Flight to Stability—Investors Prioritize In-Place Income Amid Policy Uncertainty & Rising Rates
Market Overview
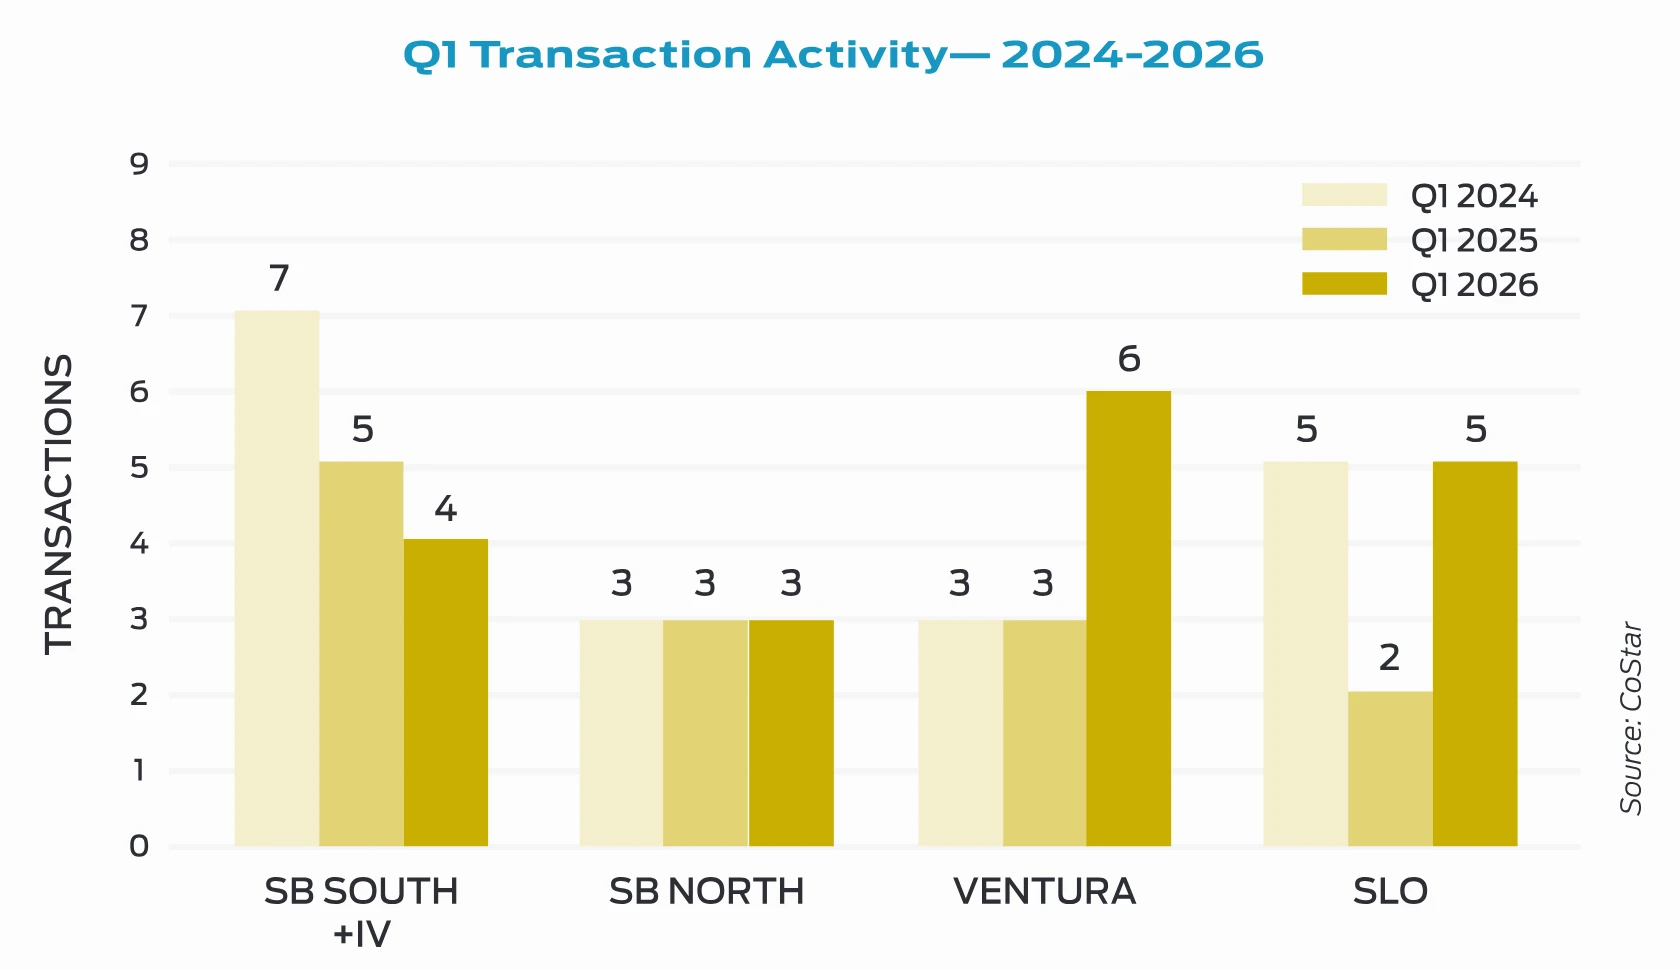
The first quarter of 2026 recorded 18 transactions of 5+ unit multifamily properties across the Central Coast, totaling $306,987,068 in combined sales volume and 857 units — matching the deal count of Q1 2024 and significantly outpacing Q1 2025’s 13 transactions. While the headline numbers are encouraging, the quarter was broadly characterized by macro and political uncertainty that weighed on underwriting confidence, particularly in the city of Santa Barbara.
On the macro side, the 10-year Treasury yield rose approximately 20 basis points over the course of the quarter, starting at around 4.16% and finishing near 4.36%. The move was not dramatic in isolation, but against a backdrop of renewed tariff concerns, mixed employment signals, and persistent inflation uncertainty, it reinforced the cautious tone that has defined multifamily underwriting since the rate hike cycle began. Buyers across all submarkets continued to prioritize in-place income over pro-forma upside, and most transactions closed with meaningful negotiation between initial ask and final price.
The most consequential local factor in Q1 was the City of Santa Barbara’s ongoing rent freeze and the broader political environment surrounding rent stabilization. The City has signaled that stringent rent cap and RSO enforcement measures are imminent, creating real underwriting uncertainty for assets subject to city jurisdiction. This dynamic shifted investor attention — and in some cases, capital — toward submarkets outside the city limits, most notably Goleta and North County. The interplay between macro rate pressure and local regulatory risk defined how capital was allocated across the Central Coast this quarter.
Santa Barbara South County—5+ Units
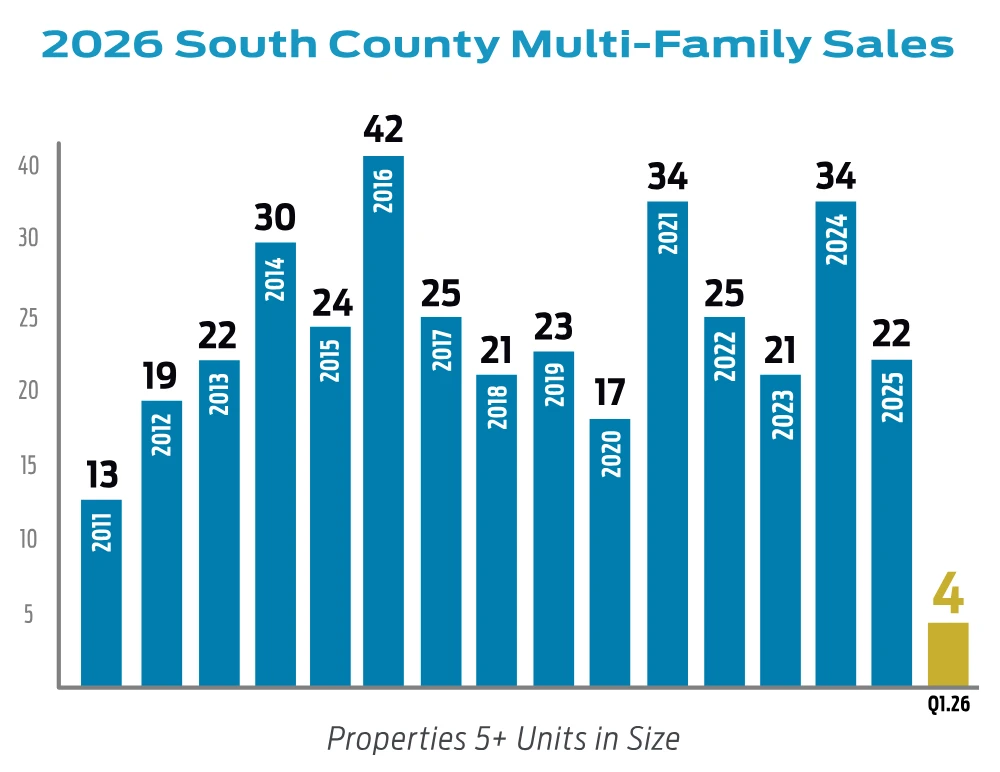
Only four transactions closed in South County for 5+ unit properties in Q1, reflecting the increasing friction that the City of Santa Barbara’s rent freeze and anticipated RSO measures are creating for buyers underwriting city assets. With a stringent rent cap broadly expected to be formalized in the near term, investors are demanding higher yields to compensate for the reduced rent growth potential, a dynamic that is widening the bid-ask gap and suppressing deal flow in the city proper. Paradoxically, stabilized assets with strong in-place income are becoming more attractive in this environment: if rent growth is effectively capped, the quality and durability of current cash flow matter more than ever, and well-occupied buildings with at-market rents carry a meaningful premium.
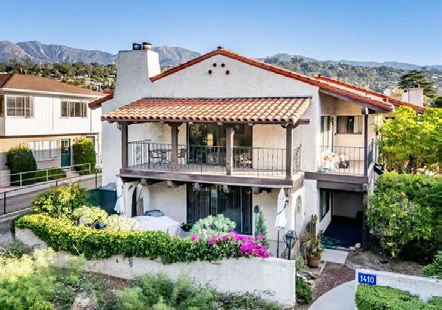
A counterintuitive beneficiary of the rent control climate is vacancy itself. In the current political environment, a building that is fully or partially vacant, while ordinarily a liability, gives a new owner the ability to set rents at market from day one, without the constraints that apply to occupied units under RSO. This was central to the story at 1410 Garden Street, a 5-unit, 1976-vintage building that sold for $3,350,000. The previous owner had systematically worked to move out tenants who had been paying significantly below-market rents, a process that both increased the property’s income potential and, critically, delivered it vacant at close. The new owner can now address deferred maintenance without tenant disruption and lease units at current market rates — a clean-slate scenario that carries real value in a market where occupied units at legacy rents are increasingly difficult to reposition.
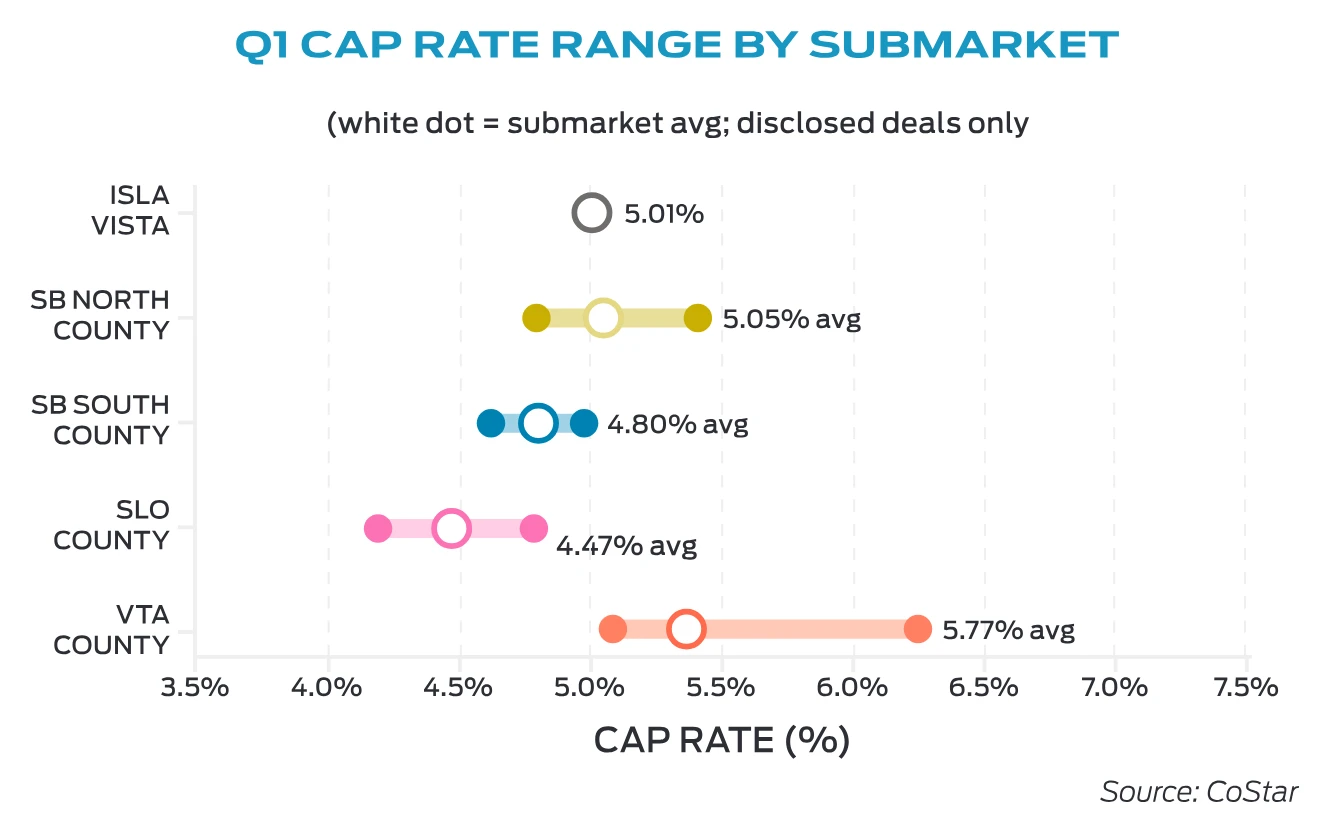
In Goleta, 23 Magnolia Avenue, a 19-unit complex, sold for $5,400,000 ($284,211/unit) at a 4.65% CAP rate. This was notable as the first 5+ unit multifamily transaction in Goleta since 2023, and it speaks to the growing investor interest in the submarket as an alternative to city of Santa Barbara assets. Goleta offers similar employment demand drivers — UCSB research, Cottage Health, the tech and semiconductor corridor along Hollister — without exposure to the city’s rent stabilization ordinance. As regulatory pressure in Santa Barbara intensifies, expect continued capital migration toward Goleta product.
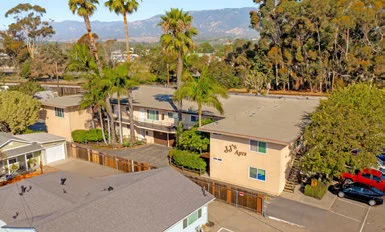
Rounding out the quarter was 601 Eucalyptus Avenue, a 6-unit all-two-bedroom building in Santa Barbara that sold for $2,750,000 ($458,333/unit) at a 4.97% CAP rate. This was a 1031 exchange acquisition, a structure that continues to be a meaningful driver of transaction activity in supply-constrained markets where buyers need to place capital within defined timelines.
Isla Vista—5+ Units
Isla Vista recorded a single transaction in Q1 2026. 6570 Del Playa Drive, a 5-unit mountainside building, sold off-market for $4,400,000 ($880,000/unit) at a 5.01% CAP rate. The IV market faces a more nuanced outlook than in prior years. UCSB has committed to growing overall enrollment and will continue to generate strong off-campus housing demand over the long term. However, the San Benito student housing project, a significant on-campus residential development currently in the pipeline, and the university’s broader initiative to house a greater share of students on campus represent a credible headwind, particularly for smaller floor plan units (studios and one-bedrooms) that compete most directly with dormitory-style housing. Larger units with multiple bedrooms and shared living configurations remain more insulated, as they cater to upperclassmen and graduate students who prefer off-campus independence. Investors underwriting IV assets should model this dynamic carefully, especially for buildings with a concentration of smaller units.
Santa Barbara North County—5+ Units
North County produced three transactions in Q1 2026 but generated $79 million in total volume, the second highest of any submarket, almost entirely on the strength of one landmark deal. 534 E. Boone Street (“Hancock Terrace”) in Santa Maria, a 272-unit, 2016-built Class A complex, was acquired by an affordable housing consortium for $75,000,000 ($275,735/unit) at a 5.4% CAP rate utilizing bond financing. The buyers plan to convert approximately 75% of units to affordable housing restricted to 50% and 80% AMI, with a nonprofit operating partner and a specialized affordable housing finance firm structuring the capital stack.
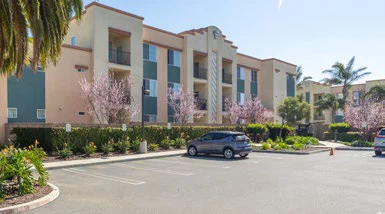
The structural implications are meaningful. Vacancy in Santa Maria has climbed in recent quarters driven by a wave of new supply deliveries, and the conversion of 200+ units away from the market-rate pool could help ease that pressure over time, benefiting the private operators who remain. The two smaller North County transactions reflect steady demand for straightforward income-producing assets. 435 E. Newlove Drive in Santa Maria, a 6-unit complex of 3BD/2.5BA townhomes, each with a two-car garage — sold for $2,215,968 ($369,328/unit) at a 4.79% CAP rate. The property had been on and off the market prior to closing and represents a quality asset for a submarket typically defined by lower price points. 215 N. Miller Street (7 units, Santa Maria), a portfolio of three structures including a 4-plex, a duplex, and a single-family home, sold for $1,810,000 ($258,571/unit) at a 4.97% CAP rate, with in-place gross rents of $143,004.
Ventura County—5+ Units
Ventura County was the most active submarket in Q1 by both deal count and dollar volume, with six transactions totaling $193.2 million across 472 units. The quarter featured two landmark institutional acquisitions alongside four private-market deals in Ventura city and Santa Paula. In Oxnard, a 235-unit, 2016-built Class A complex at 450 Forest Park Boulevard was acquired by a major institutional investor for $105,000,000 ($446,809/unit), financed with a conventional loan. In Camarillo, a 165-unit, 2003-vintage complex at 390 Paseo Camarillo traded at $69,500,000 ($421,212/unit) in an institutional-to-institutional transaction. Both deals reflect durable long-term conviction in Ventura County’s supply-constrained coastal markets and provide a meaningful pricing anchor for surrounding Class B and C product.
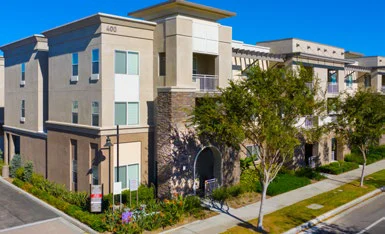
Across the four private-market deals, the most instructive dynamic was the widening gap between North and South Oxnard as distinct investment environments. 560 W. Gonzales Road, a 24-unit, 1960-vintage asset in North Oxnard, sold for $6,000,000 ($250,000/unit) at a 5.98% CAP rate with five Section 8 tenants providing an income floor. […] South Oxnard has been experiencing elevated turnover in recent quarters […]. This is a dynamic worth monitoring closely, as higher turnover carries real carrying costs and can affect underwritten stabilized income.
The remaining private deals in Ventura city and Santa Paula reflected the classic value-add vintage acquisition thesis. 3980 Telegraph Road, the underlying land for a 28-unit townhouse complex on an expiring ground lease, with the buyer expected to assume control of the improvements upon lease expiration, closed for $6,400,000 ($228,571/unit). 92–114 E. Center Street (12 units, Ventura) sold at a 6.24% CAP rate, the highest disclosed yield in the submarket this quarter. 327–331 S. Steckel Drive (8 units, Santa Paula) rounded out the quarter at $2,462,500 ($307,813/unit) at 5.09%, with one Section 8 tenant in place.
San Luis Obispo County—5+ Units
SLO County rebounded meaningfully in Q1 2026 with five transactions, up from just two in Q1 2025, spanning the city of SLO, Pismo Beach, and Grover Beach. The largest deal was 2804 Augustina Street in San Luis Obispo, a 25-unit, all-one-bedroom complex built in 1970 that sold for $7,200,000 ($288,000/unit). With rents well below market, the listing agent cited a proforma CAP rate approaching 6.5% at stabilization — the clearest value-add play of the quarter on the Central Coast, anchored by Cal Poly’s reliable demand base.
Pismo Beach contributed two coastal premium transactions. 172 Ocean View Avenue, a 1928-built 8-unit property with two detached cottages, sold for $2,640,000 ($330,000/unit) at a 4.19% CAP rate. 2570 Spyglass Drive (5 units) sold for $1,945,000 with one vacant unit offering immediate rent mark-up opportunity. In SLO proper, 1771 Johnson Avenue, a fully occupied 9-unit townhome complex built in 2010 with one-car garage per unit, opened the quarter at $3,728,600 ($414,289/unit, 4.78% CAP), representing the premium commanded by newer, stabilized product in the market. A two-property portfolio in Grover Beach (18 combined units) rounded out the quarter at an estimated $4,310,000 at a 4.7% CAP rate.
Summary
Q1 2026 delivered 18 transactions and $307 million in total volume across the Central Coast, a strong headline number that nonetheless came with an asterisk of uncertainty. A rising 10-year Treasury, macro volatility, and local regulatory pressure in the city of Santa Barbara all weighed on buyer conviction, particularly for assets inside city limits. The result was a flight toward clarity: investors sought properties with strong in-place income, manageable leverage, and limited exposure to the regulatory ambiguity that has come to define underwriting in the city of Santa Barbara.
The Santa Barbara rent freeze and the broadly anticipated passage of stringent RSO measures represent the most significant near-term variable for South County investment activity. Rather than dampening demand entirely, this dynamic is somewhat redistributing capital, toward Goleta (which saw its first 5+ unit sale since 2023), toward 1031 exchange buyers absorbing stabilized assets on compressed timelines, and toward properties with vacant units that offer a clean rent-setting opportunity. The premium on current income quality over pro-forma rent growth has never been higher in this submarket.
Elsewhere on the Central Coast, the macro picture was more straightforward. Institutional capital continued to validate Ventura County’s fundamentals with two landmark trades, though the emerging bifurcation between North and South Oxnard […] warrants closer attention from operators in that market. SLO County’s Q1 rebound to five transactions reflects an improving equilibrium between buyer and seller expectations, with value-add appetite leading the way. And the Hancock Terrace affordable housing conversion in Santa Maria represents a structural supply intervention that should benefit private operators as the market digests its recent delivery pipeline.
Looking ahead to Q2, the primary variables are the trajectory of the 10-year Treasury, the finalization of Santa Barbara’s rent control framework, and the pace of new supply absorption in Santa Maria and Camarillo. The Central Coast’s underlying demand fundamentals — constrained supply, coastal lifestyle premium, university and healthcare employment anchors — remain intact. Investors who underwrite to current income and realistic stabilized assumptions will continue to find a range of opportunities across the risk/return spectrum throughout 2026.
Multifamily Investments: 2–4 Units
Contribution by Aneta Jensen
The first quarter of 2026 recorded 17 closed sales of 2–4 unit residential income properties across South Santa Barbara County, marking a notable increase from Q1 2025, which saw only 8 transactions, all within the City of Santa Barbara. This reflects a meaningful rebound in transaction volume despite a more complex and restrictive regulatory environment.
Of the 17 sales, 15 occurred in Santa Barbara, one in Goleta, and one in Carpinteria, reinforcing the continued concentration of activity within the Santa Barbara core market. Duplexes dominated the landscape, accounting for 15 of the 17 transactions, while 2 triplexes sold, and no fourplexes traded during the quarter.
South Santa Barbara County | 2–4 Units (Excluding Isla Vista)
From a pricing standpoint, duplexes achieved an average sale price of $1,901,000, or $950,500 per unit, while triplexes averaged $1,757,402, or $585,801 per unit. While duplexes continue to command a higher price per unit, both duplexes and triplexes benefit from strong owner-user demand, as buyers are able to utilize residential financing and offset mortgage payments with rental income. This structure, which incorporates both personal income and projected rental income, makes these smaller multifamily assets highly accessible and attractive entry points into the Santa Barbara market. As a result, pricing remains supported by a broad buyer pool consisting of both investors and long-term owner-users.
The regulatory backdrop remains one of the most influential factors shaping buyer behavior and valuation. While early 2025 was marked by uncertainty surrounding renovictions, the current market is operating under more restrictive tenant protection policies. The City of Santa Barbara’s rent freeze, along with evolving rent stabilization measures, continues to limit landlords’ ability to increase rents in line with rising operating costs. At the state level, AB 1482 applies broadly, with limited exemptions for single-family residences, condominiums, and owner-occupied duplexes. As a result, most small income properties fall under both state and local regulations, requiring buyers to place greater emphasis on in-place income, vacancy potential, and long-term operational constraints.
Q1 2025 vs Q1 2026 2–4 Unit Market Comparison
| 2026 SALES | 2025 SALES | Δ SALES (%) | AVG PRICE (2026) | AVG PPU (2026) | PRIOR PPU (2025) | Δ PPU (%) | |
|---|---|---|---|---|---|---|---|
| DUPLEX | 15 | 5 | 8.1% | $1,901,000 | $950,500 | $879,283 | 8.1% |
| TRIPLEX | 2 | 2 | 6.0% | $1,757,402 | $585,501 | $552,292 | 6.0% |
| FOURPLEX | 0 | 1 | — | — | — | — | — |
| 17 | 8 | 112.5% | — | — | — | — |
Note: Fourplex data unavailable for 2026; PPU averages exclude Fourplex and Total rows.
Despite these headwinds, small residential income properties remain highly desirable across a wide range of buyers. Duplexes and triplexes, in particular, offer a unique opportunity for owner-users to enter the Santa Barbara market while offsetting housing costs. The ability to qualify for residential loans—combined with more accessible down payment requirements compared to larger multifamily properties—continues to expand the buyer pool. Consequently, valuation in this segment is driven less by cap rates and more by factors such as condition, livability, and the potential to achieve market rents.
As is typical, the first quarter reflects a slower start to the year following a strong fourth quarter, with activity expected to build into the spring and summer months.
Triplex
Average Sold Price: $1,757,402 | Average Sold PPU: $585,801
Several transactions during the quarter illustrate the range of opportunities and pricing dynamics within the market. The only sale in Goleta, 4593 Hollister Avenue, featured a 3-bedroom, 1.5-bath main residence along with two detached studios on a sizable 0.41-acre lot. Despite being fully occupied, the property traded after just seven days on the market, driven by its strong value-add potential, including opportunities for ADU development and future rent growth. Originally listed at $1,249,000, the property ultimately sold for $1,561,250 following a short, sub-30-day escrow.
In Santa Barbara, 21 E Arrellaga Street, the only triplex sale in the city, closed at $1,953,553, or $651,184 per unit. The property was delivered vacant following a prolonged escrow due to probate, providing the buyer with a clean slate to renovate and lease at market rates. This vacancy-driven upside continues to be a key value driver in the current regulatory environment.
Duplex
Average Sold Price: $1,901,000 | Average Sold PPU: $950,500
At the high end of the market, 428 Corona Del Mar, Santa Barbara achieved the highest sale price and price per unit of the quarter, closing at $3,125,000, or $1,562,500 per unit. Located in the highly desirable East Beach area, the property was delivered fully vacant and renovated, and had previously operated as a short-term vacation rental. Its premium location and turnkey condition allowed it to command top-of-market pricing.
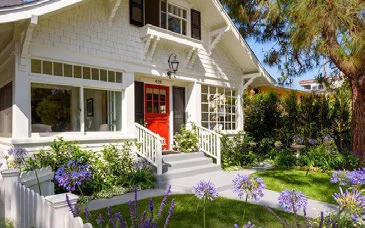
Conversely, 220 W Figueroa Street was among the lowest sales of the quarter, closing at $1,400,000 after 151 days on the market. Originally built in 1895 and in near tear-down condition, the property’s value was driven primarily by its expansive lot size (over 10,000 square feet) and favorable R-4 zoning, which supports higher-density redevelopment. The asset consisted of a 2-bedroom, 1-bath historic residence along with an attached legal one-bedroom junior ADU, was delivered vacant, presenting an ideal opportunity for a buyer with a contractor-oriented skill set to capitalize on land value and future development potential rather than relying on in-place income.
The only sale in Carpinteria was a duplex located on Carpinteria Street, backing to the Carpinteria Salt Marsh Reserve and situated on a large 0.26-acre lot zoned CPD/R. ( Commercial Planned Development/Residential ) the property represents a compelling example of how zoning flexibility can drive value beyond current income. This flexibility is particularly attractive for investors seeking to unlock higher density residential or mixed use project in supply constrained coastal markets. The property was listed at $1,749,999 and sold for $1,731,000. Despite being tenant-occupied, the property went into escrow just 2 days after hitting the market, underscoring the strong demand for well-located assets with redevelopment potential.
South Santa Barbara County Market Summary
Based on the first quarter data, the South Santa Barbara County 2–4 unit market is showing improved activity, with 17 closed transactions indicating stronger buyer participation compared to last year. At the same time, supply remains steady, with 26 active listings and 19 new properties coming to market during the quarter, suggesting that inventory is keeping pace with demand.
Duplexes remain the most sought-after asset type, driven by strong owner-user demand, their appeal as an alternative to single-family homes, and the relatively low level of management expertise required to operate them.
The average price per unit for duplexes this quarter reached $950,500, showing a strong increase compared to $879,283 in Q4 2025—an approximate 8.1% rise. Similarly, triplexes experienced growth, with the average price per unit increasing to $585,801 from $552,292 in the previous quarter, reflecting a 6% increase.
The limited pending activity, with only 3 properties going under contract during the quarter, shows that buyers are still cautious and selective. Overall, the market appears balanced, with buyers placing strong emphasis on pricing, condition, and immediate usability when making decisions.
Future Outlook
Looking ahead, the data suggests the market should continue to improve gradually, especially if interest rates stabilize or begin to decline. That said, because there is still a steady amount of inventory available, price growth will likely remain limited, and sellers will need to stay realistic with pricing to attract buyers.
Properties with clear upside—such as vacant units, renovation potential, or the ability to add ADUs—are expected to perform better, as buyers are prioritizing opportunities to increase income. In contrast, properties with below-market rents and limited upside may take longer to sell.
Overall, the upward movement in price per unit across all 2–4 unit asset types, coupled with an increase in transaction volume within this segment, highlights continued buyer demand and strong support for well-located small multifamily properties. Despite broader market constraints—including regulatory pressures—these assets demonstrate greater resilience to tightening policies, driven by the flexibility of the owner-user component, more accessible financing qualification, and a lower barrier to entry for buyers.
Isla Vista Student Housing SFR & 2–4 Unit Segment
Isla Vista saw strong activity in the student housing segment during the first quarter of 2026, despite recording zero sales. A total of 8 new listings came to market, with 3 properties going pending and one closed listing recorded during the quarter. In comparison, Q1 2025 recorded two closed transactions, indicating a slight slowdown in completed sales despite continued buyer interest.
Of the properties brought to market, five were duplexes and three were single-family homes. Two of the listings were located on Del Playa—one on the bluff side and one on the mountain side. Bluff-front properties typically draw strong interest but can also raise concerns related to coastal erosion, which may influence buyer decision-making. Most of the listings featured three-bedroom units or larger, aligning with typical student housing demand.
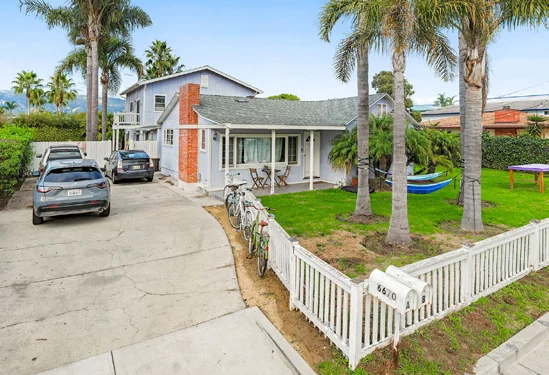
Two properties received multiple offers and entered escrow during Q1 after a short time on the market. One notable example was 6789 Sabado Tarde, which was listed at $1,800,000 and closed at the beginning of Q2 for $1,820,000, exceeding its asking price.
Another pending transaction was a duplex located at 6670 Sueno, which is in contract to a local investor and is expected to close at the beginning of Q2. The property attracted strong interest due to its development potential, particularly related to the larger lot size, which presents opportunities for future expansion or redevelopment.
Overall, advertised cap rates (4.68%–6.24%) reflect continued investor interest in Isla Vista student housing despite a more measured transaction pace.
While the City of Santa Barbara continues to tighten regulations on rental housing, Isla Vista remains subject to AB 1482 rent control, which is generally less restrictive. Given the annual turnover typical in student housing, property owners are often able to adjust rents to market levels more frequently than in traditional rental markets.
Student Housing vs Traditional 2–4 Units
It is worth noting that student housing properties—both 2–4 unit assets and single-family homes operated as student rentals— tend to trade primarily on a rental income basis, unlike traditional 2–4 unit properties, where valuation places greater emphasis on a price-per-unit basis.
Future Outlook
Isla Vista student housing is expected to remain one of the most active and resilient markets for real estate investment in the region. With current inventory on the market and a noticeable shift in investor focus away from the City of Santa Barbara, Isla Vista continues to attract capital seeking more stable and predictable submarkets. Investors are increasingly drawn to the area’s proven profitability and the ability to consistently reset rents to market levels due to the annual tenant turnover inherent in student housing.